Read the full deal writeup
Sign up for a free Accredited account to read the editorial writeup, financials, and broker contact for this deal.
Full Editorial Writeup
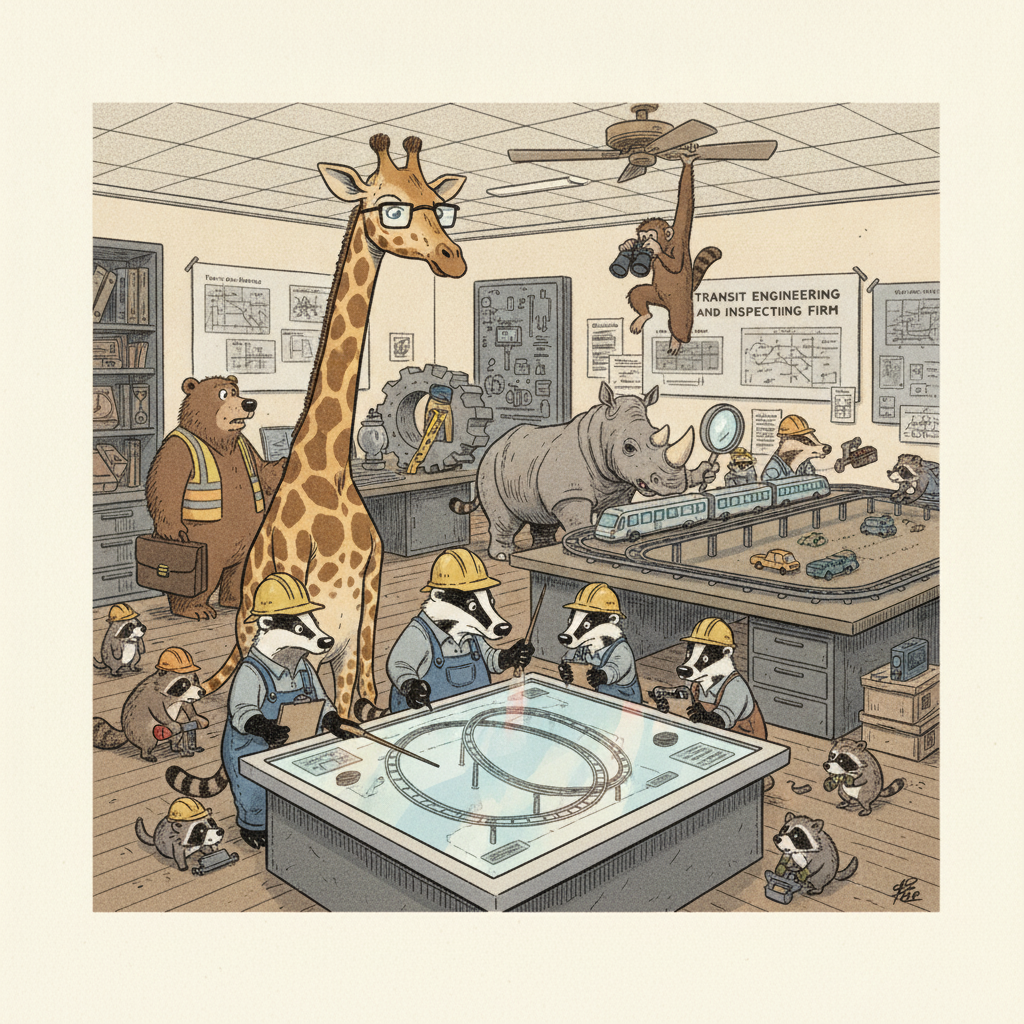
This is an engineering and technical consulting firm serving the U.S. public transit sector from planning through operations. Its engineers help agencies plan, specify, and review new vehicles and systems, while its resident inspectors sit inside manufacturer plants (domestic and overseas, including Japan, South Korea, and Canada) to oversee vehicles through testing and acceptance. The firm works through all major engineering primes to reach marquee transit agencies including LA Metro, NYC Transit, Sound Transit, WMATA, NJ Transit, Amtrak, Illinois DOT, SEPTA, and MBTA.
The financial profile is the headline. Revenue of roughly $11.4m generates about $2.35m of adjusted EBITDA, and margins have expanded sharply, with gross margin averaging 54.5% from 2023 to 2025 and EBITDA margin climbing from 9.9% to 20.9% over that window. More than 90% of annual revenue comes from repeat clients, and the company reports a backlog near $20.5m with task orders running through 2032. That is unusually strong revenue visibility for a professional services firm.
What makes this niche durable is its tie to federally funded, long-cycle infrastructure. Transit vehicle fleets are aging (roughly a third of U.S. rail fleets are past useful life), and tightening Buy America domestic content rules make the firm's pre-award and post-delivery compliance audits essential to agencies securing federal money. The business operates from three leased offices with assumable leases, so there is no real estate to buy, and the three selling shareholders are retiring and will support a transition.
Why we like it
- Earnings quality is strong and improving: $2.35m EBITDA on $11.4m revenue at a 20.9% margin, up from 9.9% two years earlier, with 54.5% average gross margins. The margin expansion suggests real operating leverage and disciplined project pricing rather than a one-time revenue spike.
- The moat is regulatory and relational. Over 90% of revenue is repeat business from engineering primes the firm has worked with for decades, and its Buy America audit expertise is a specialized, federally mandated capability that agencies cannot easily skip. Resident inspectors embedded in plants in Japan, South Korea, and Canada are hard to replicate quickly.
- Market tailwinds are concrete, not speculative. Roughly a third of U.S. rail transit fleets are past useful life, driving a multi-year replacement cycle, and tightening domestic content rules increase the need for the firm's compliance and inspection work. A $20.5m backlog with task orders through 2032 turns those tailwinds into booked revenue.
- 280-Location California ATM Route, Alameda County Cash-Handling Business
- 275-Location ATM Portfolio, Duval County FL
- 270-Unit Florida ATM Route, Duval County, Professionally Managed
- 275-Unit ATM Route, San Francisco County
- Multi-State ATM Portfolio, ~250 Terminals, Fully Managed
- Northern California ATM Network, 242 Managed Locations
Want the full analysis on every deal? Unlock the complete platform with Accredited Pro to screen live listings and read our operator-level writeups.